3009 Ridge Court, Unit 14, Olympic Valley, California
3 BR | 2 BA | 1,421 SF
Sale Price $1,100,000.00
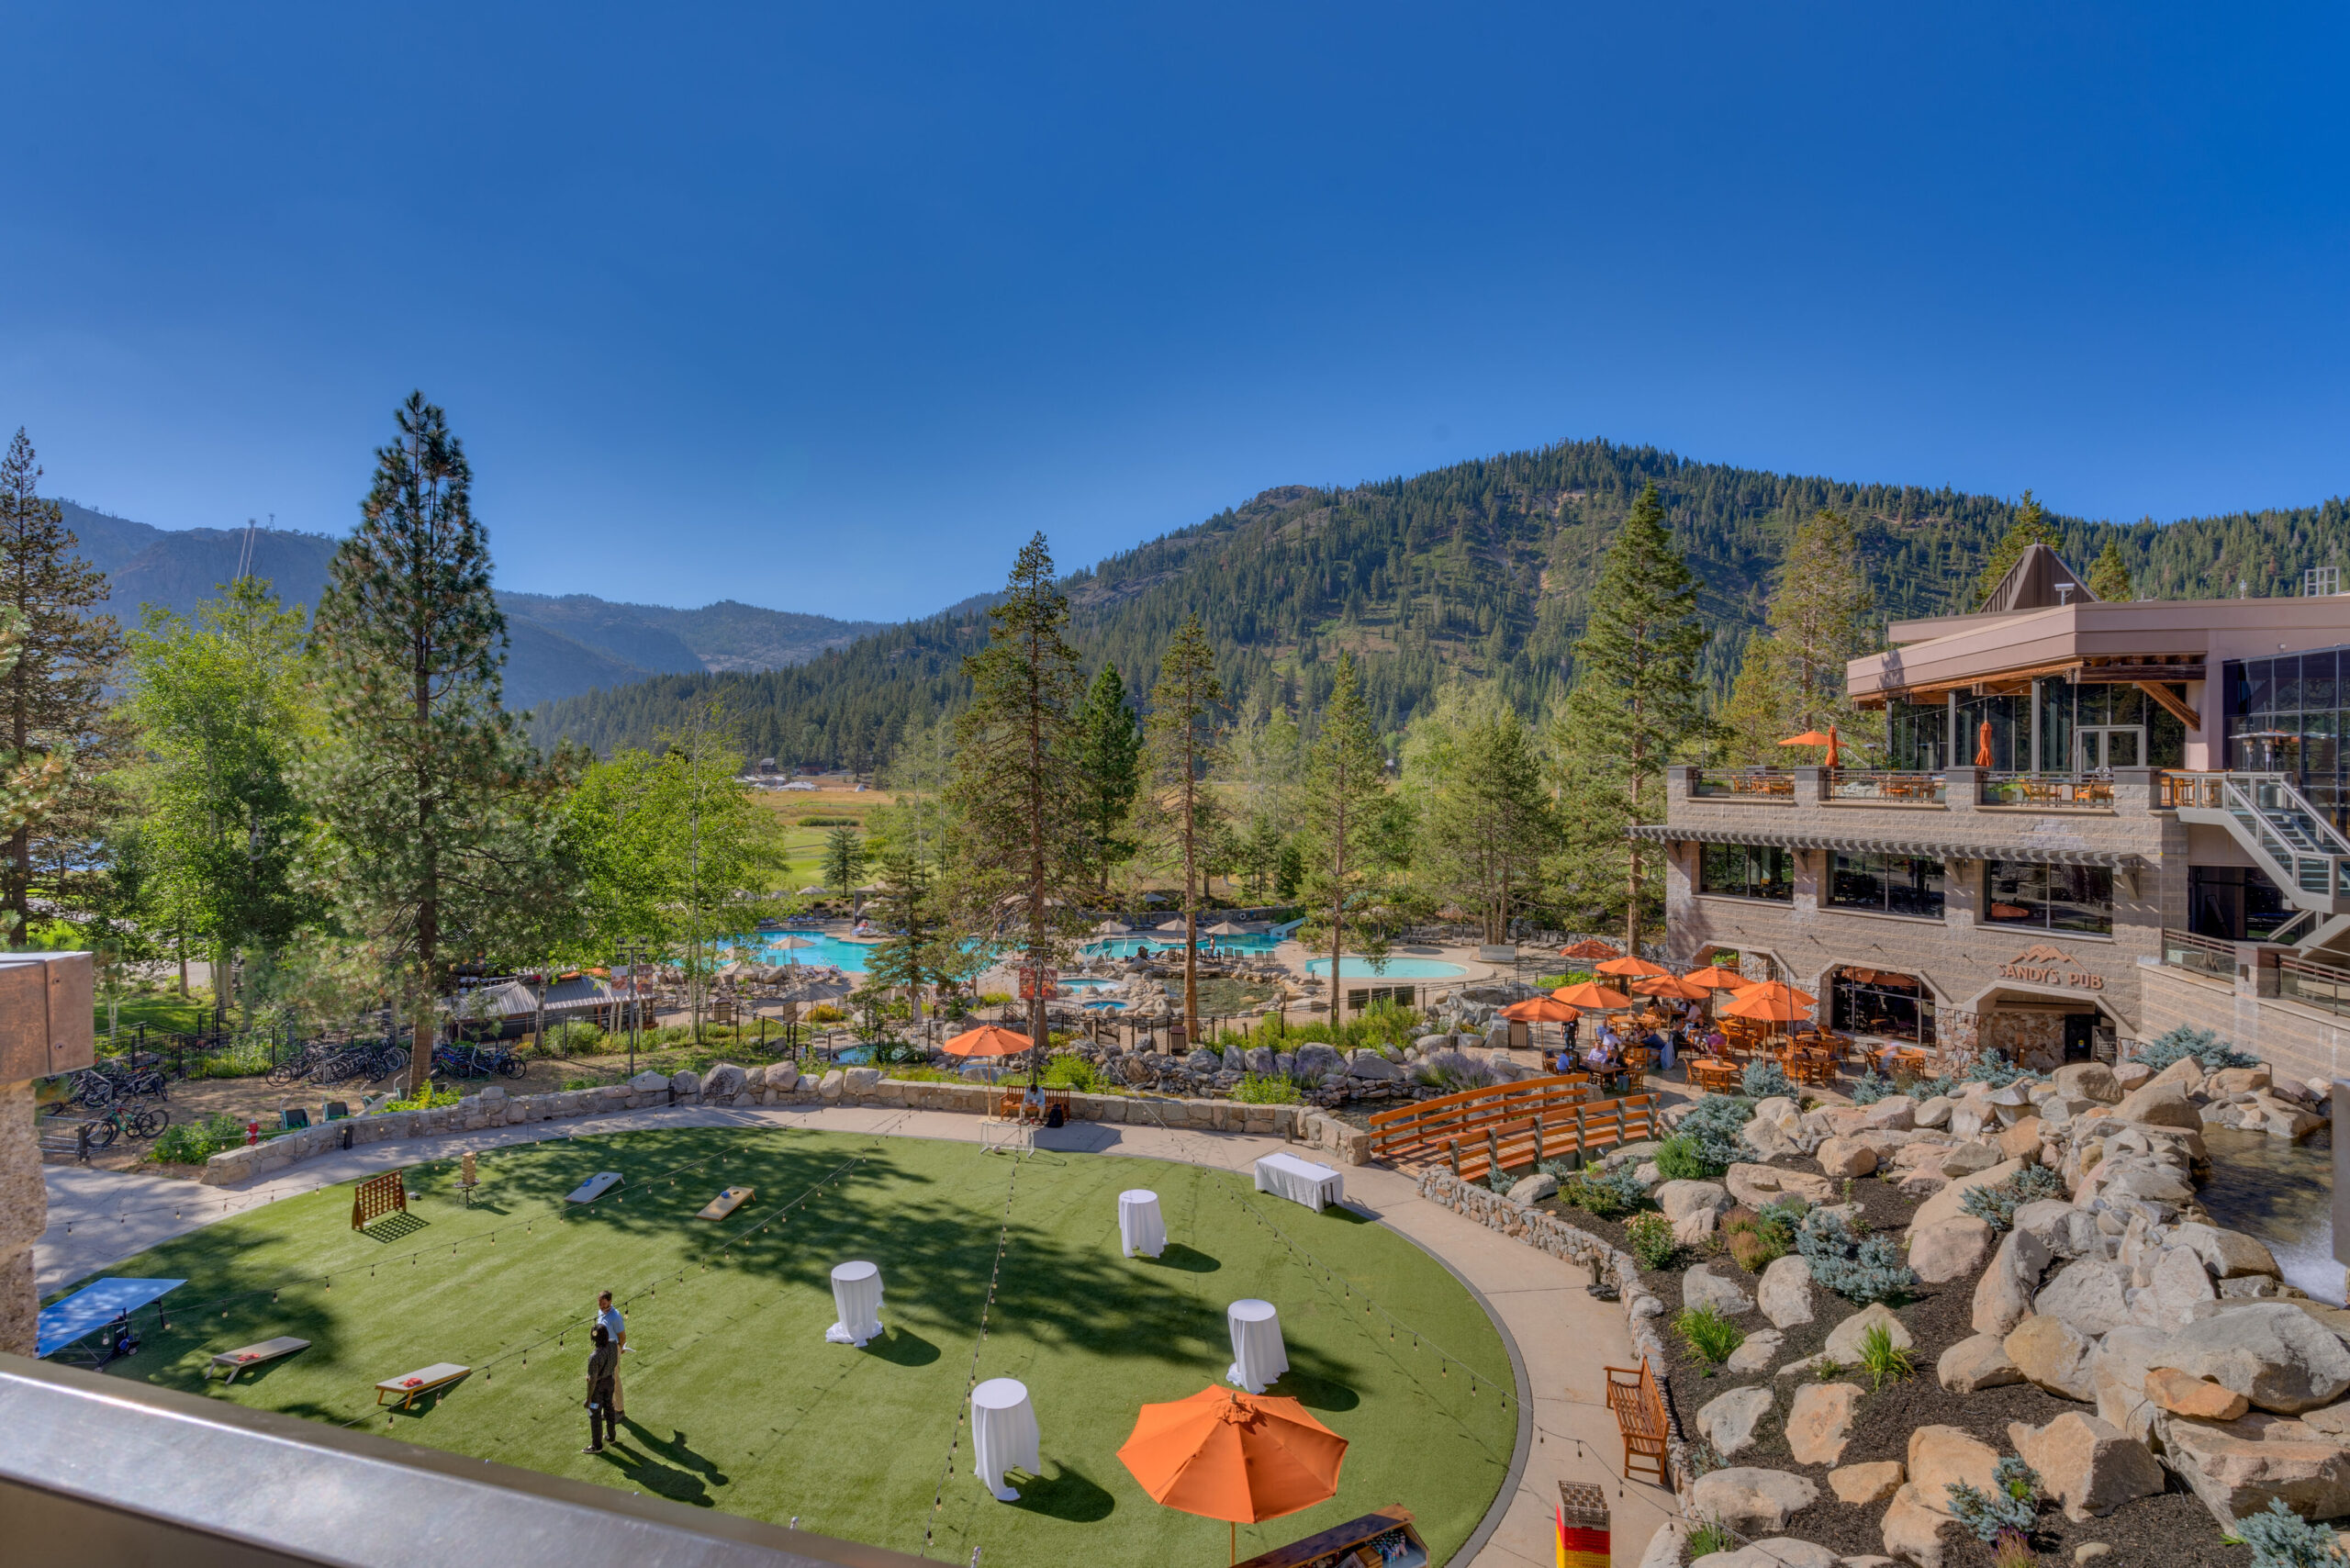
The perfect resort-like lifestyle in Olympic Valley for all Tahoe seasons. Centrally located to countless dining and shopping options, trail access, bike paths to Tahoe City and West/North Shore, and Truckee River. Congratulations to our buyers who get to enjoy it!
For more information on Olympic Valley real estate, contact Amie Quirarte.
We represented the seller of these two units at Everline Resort (formally Squaw Creek), and couldn’t be more excited for our clients to take their next steps of homeownership in our area. We put this property in escrow within 4 days of listing it with a full price offer.
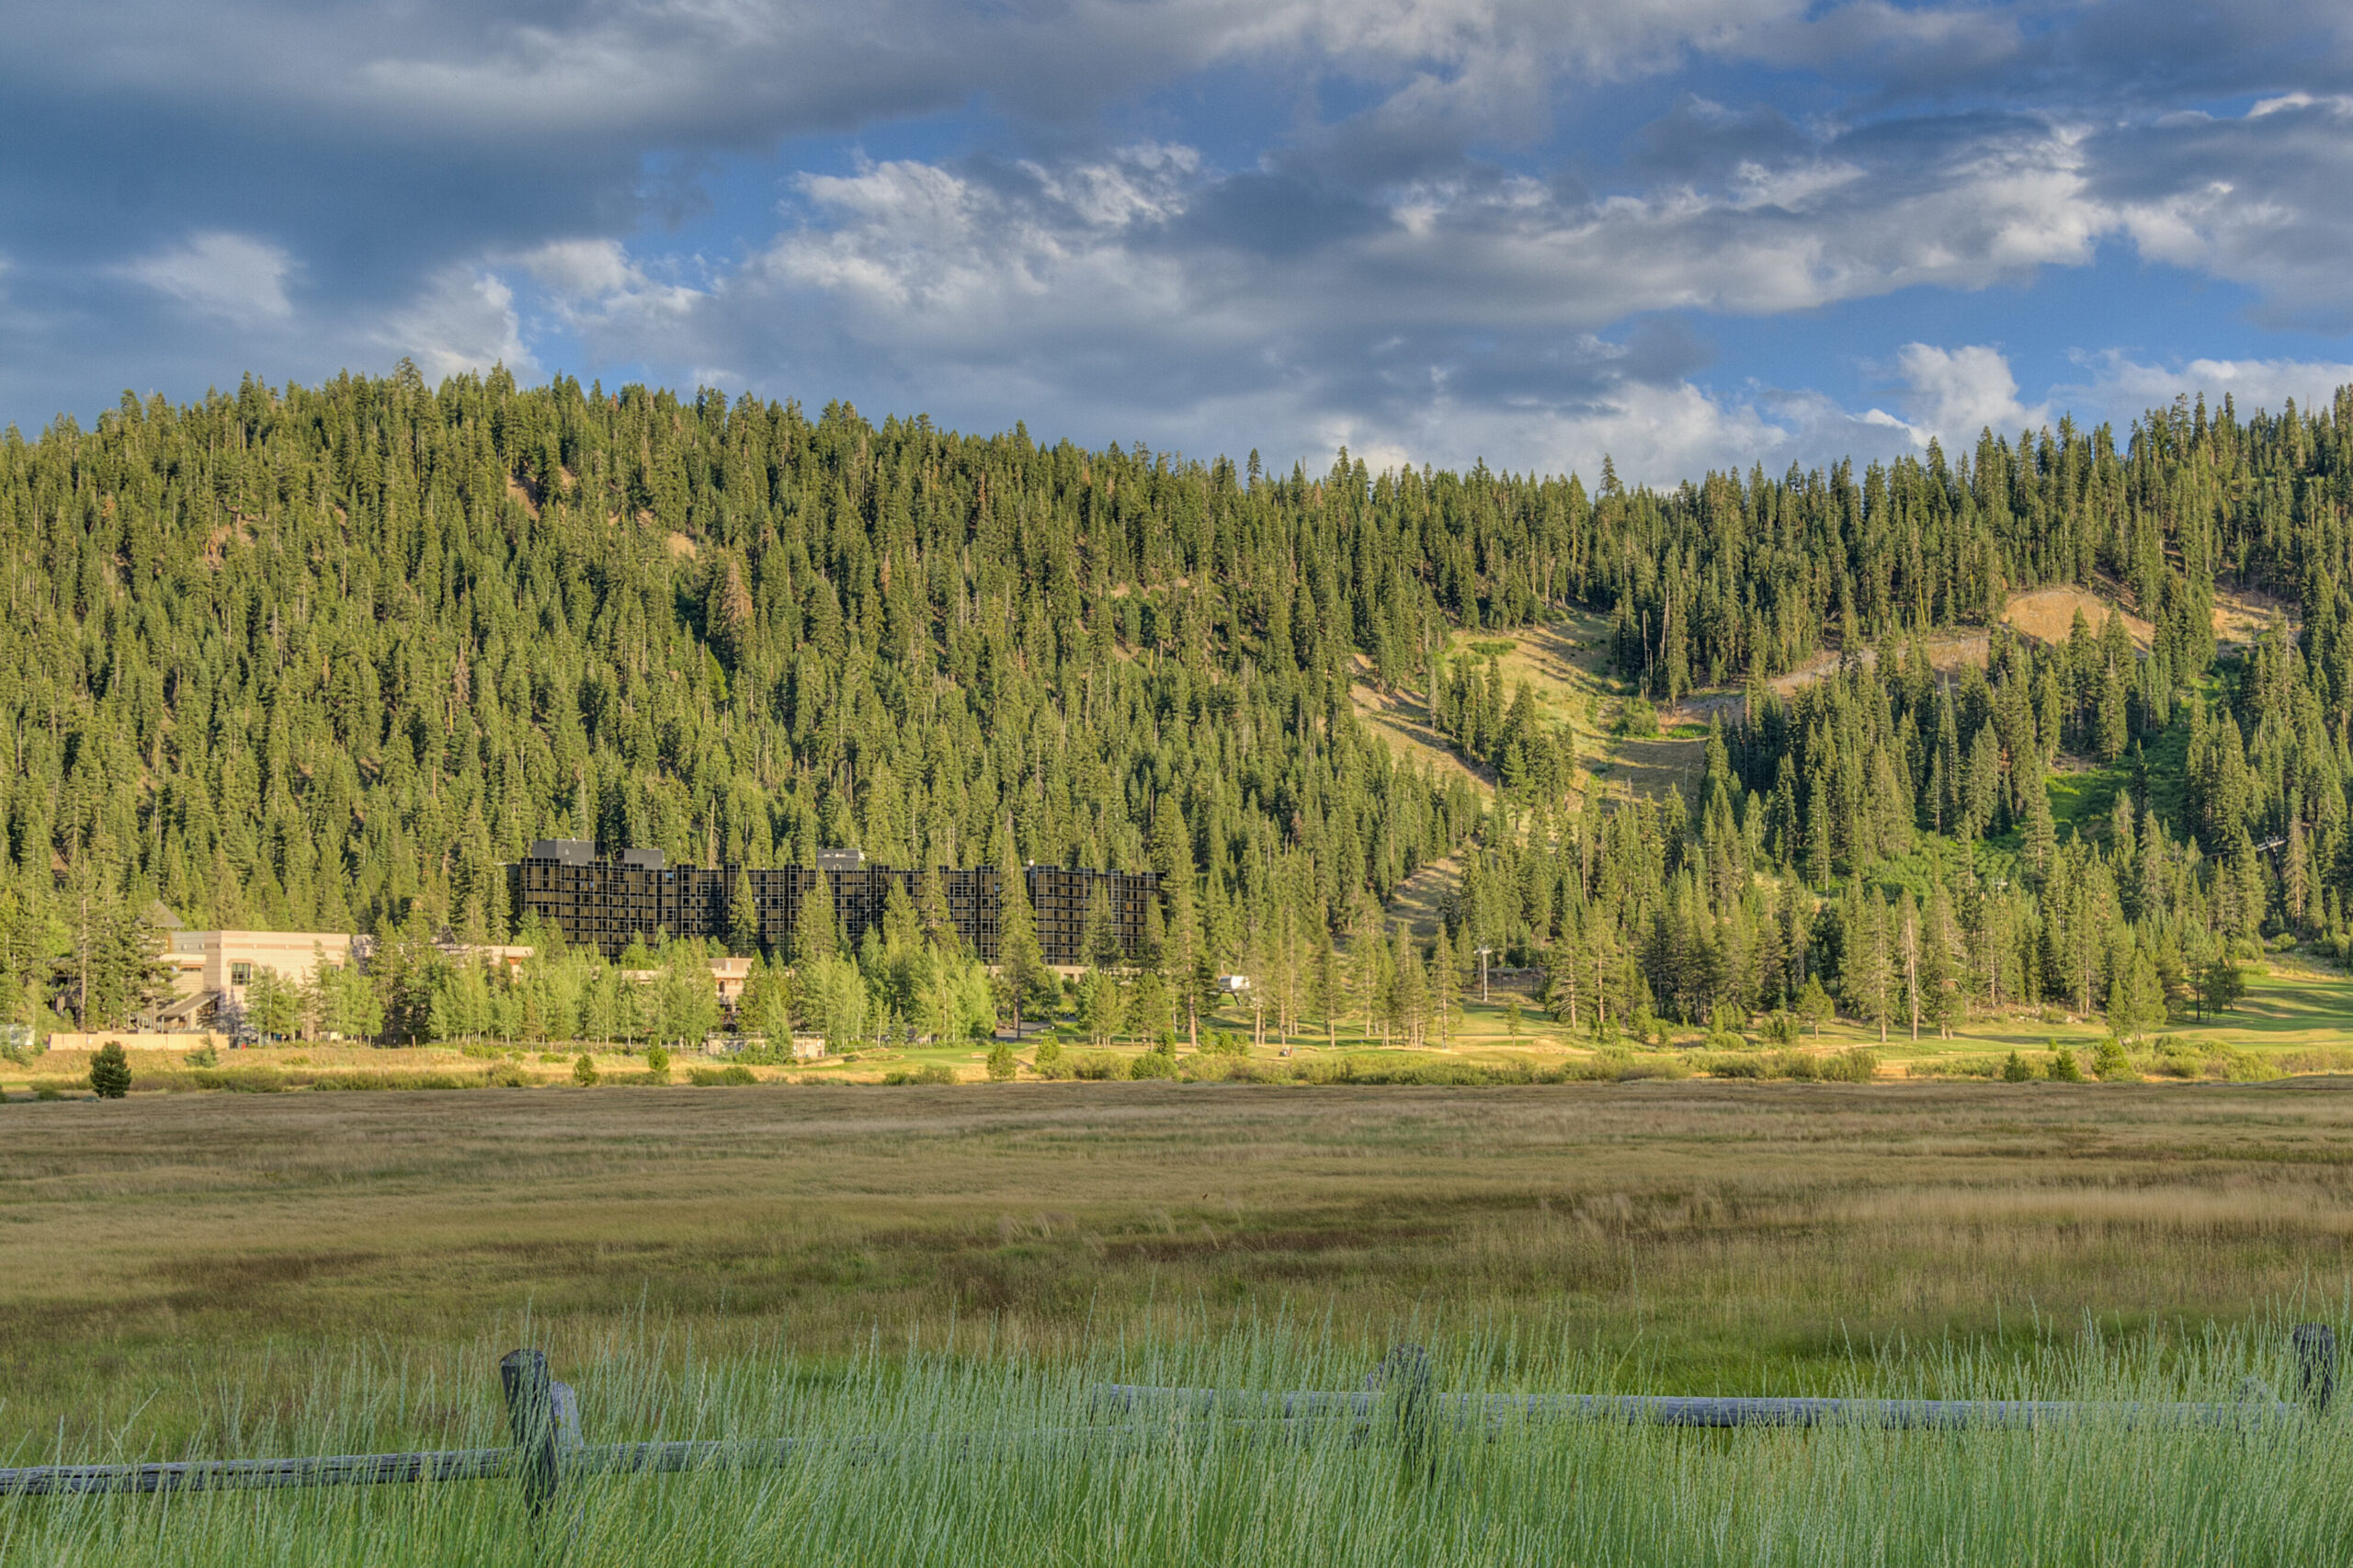
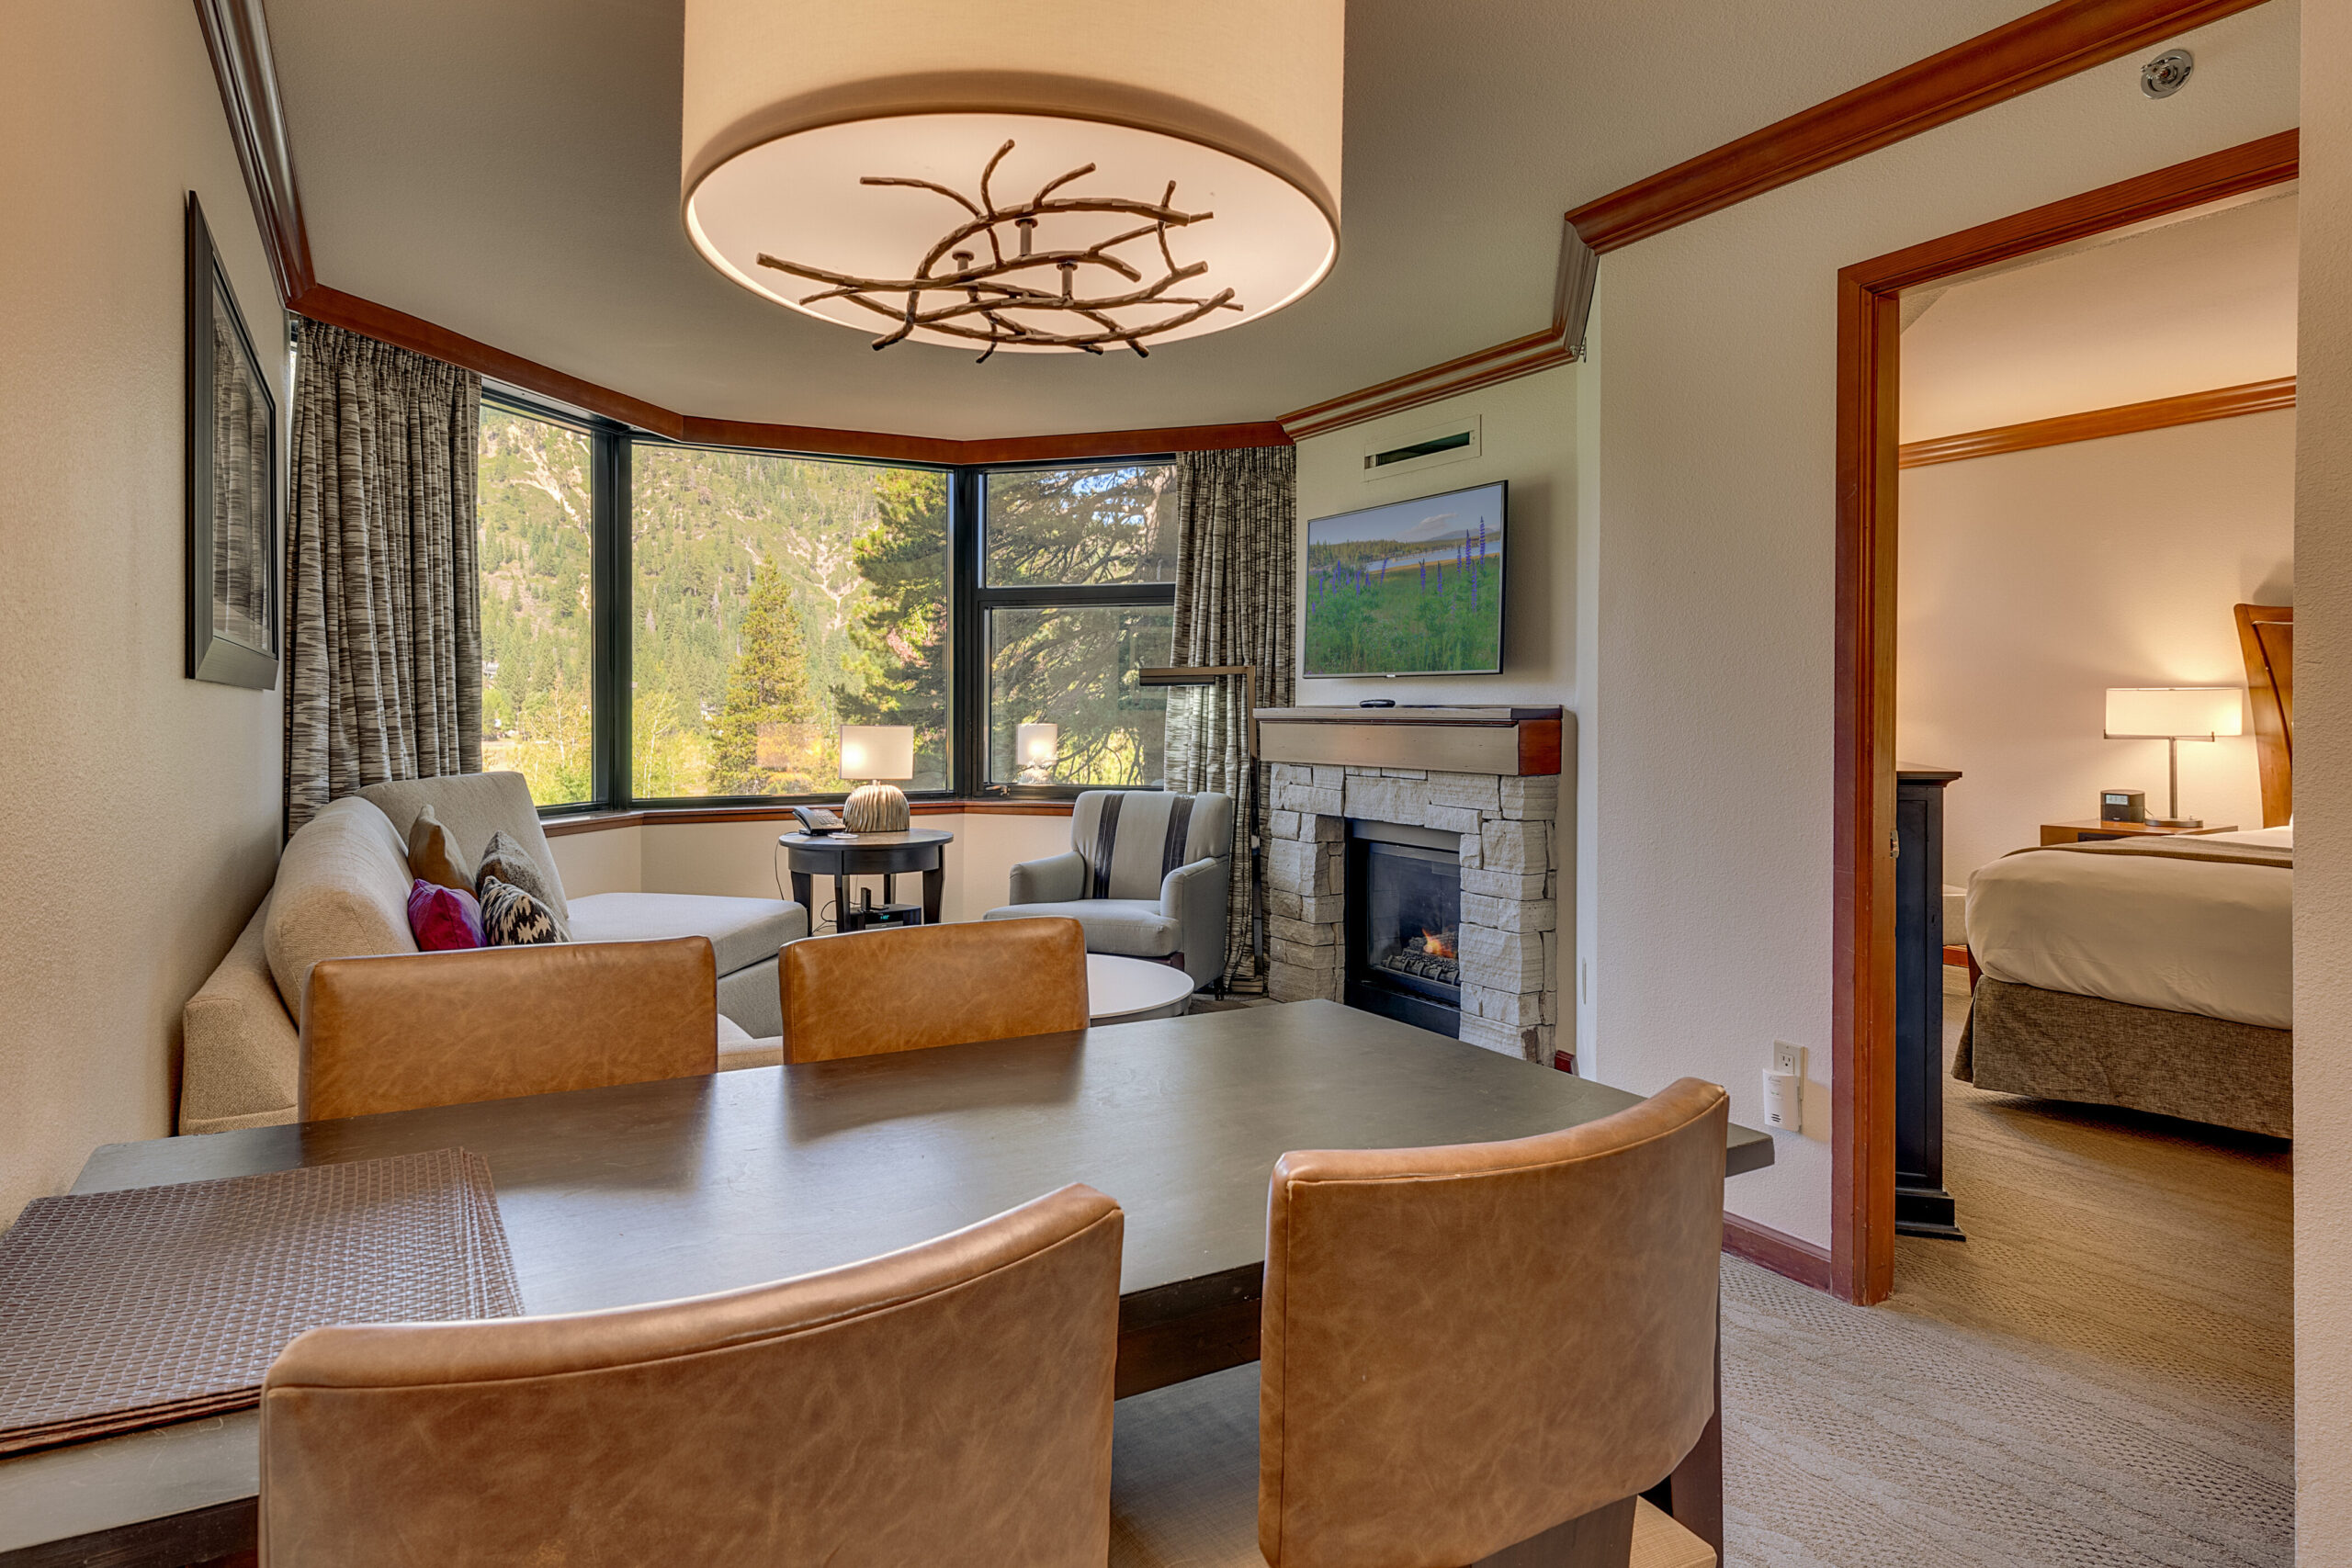
This beautiful two-bedroom condo has breathtaking views of the Olympic Valley area, Resort Chair, and mountain run; offering a great balance between owner usage and rental opportunities.
For information on Olympic Valley properties, contact Amie Quirarte.
Located just a few blocks from Lake Tahoe Park, the private HOA beach and recreation area, this home is your idyllic West Shore retreat. The attached living space/kitchenette/bathroom has a separate entrance, and can be closed off from the main home. This extensively remodeled home has four bedrooms, four bathrooms, a separate living area, and ample space for you and all of your visitors. The fully fenced backyard and large deck allow maximum optimization for your outdoor time, no matter what the season.
Located in the center of town, this industrial building in Incline Village checked off all the marks for the new owners who wanted to find commercial space. Lake Tahoe, generally speaking, commands high prices for real estate because there simply just isn’t any more space for new homes or buildings. Because of this and the complicated intricacies of the TRPA, commercial or warehouse space is even harder to find. With much delight, the buyers knew they found the right property and sealed the deal. Congratulations!
For more information on Incline Village real estate, contact Amie Quirarte.
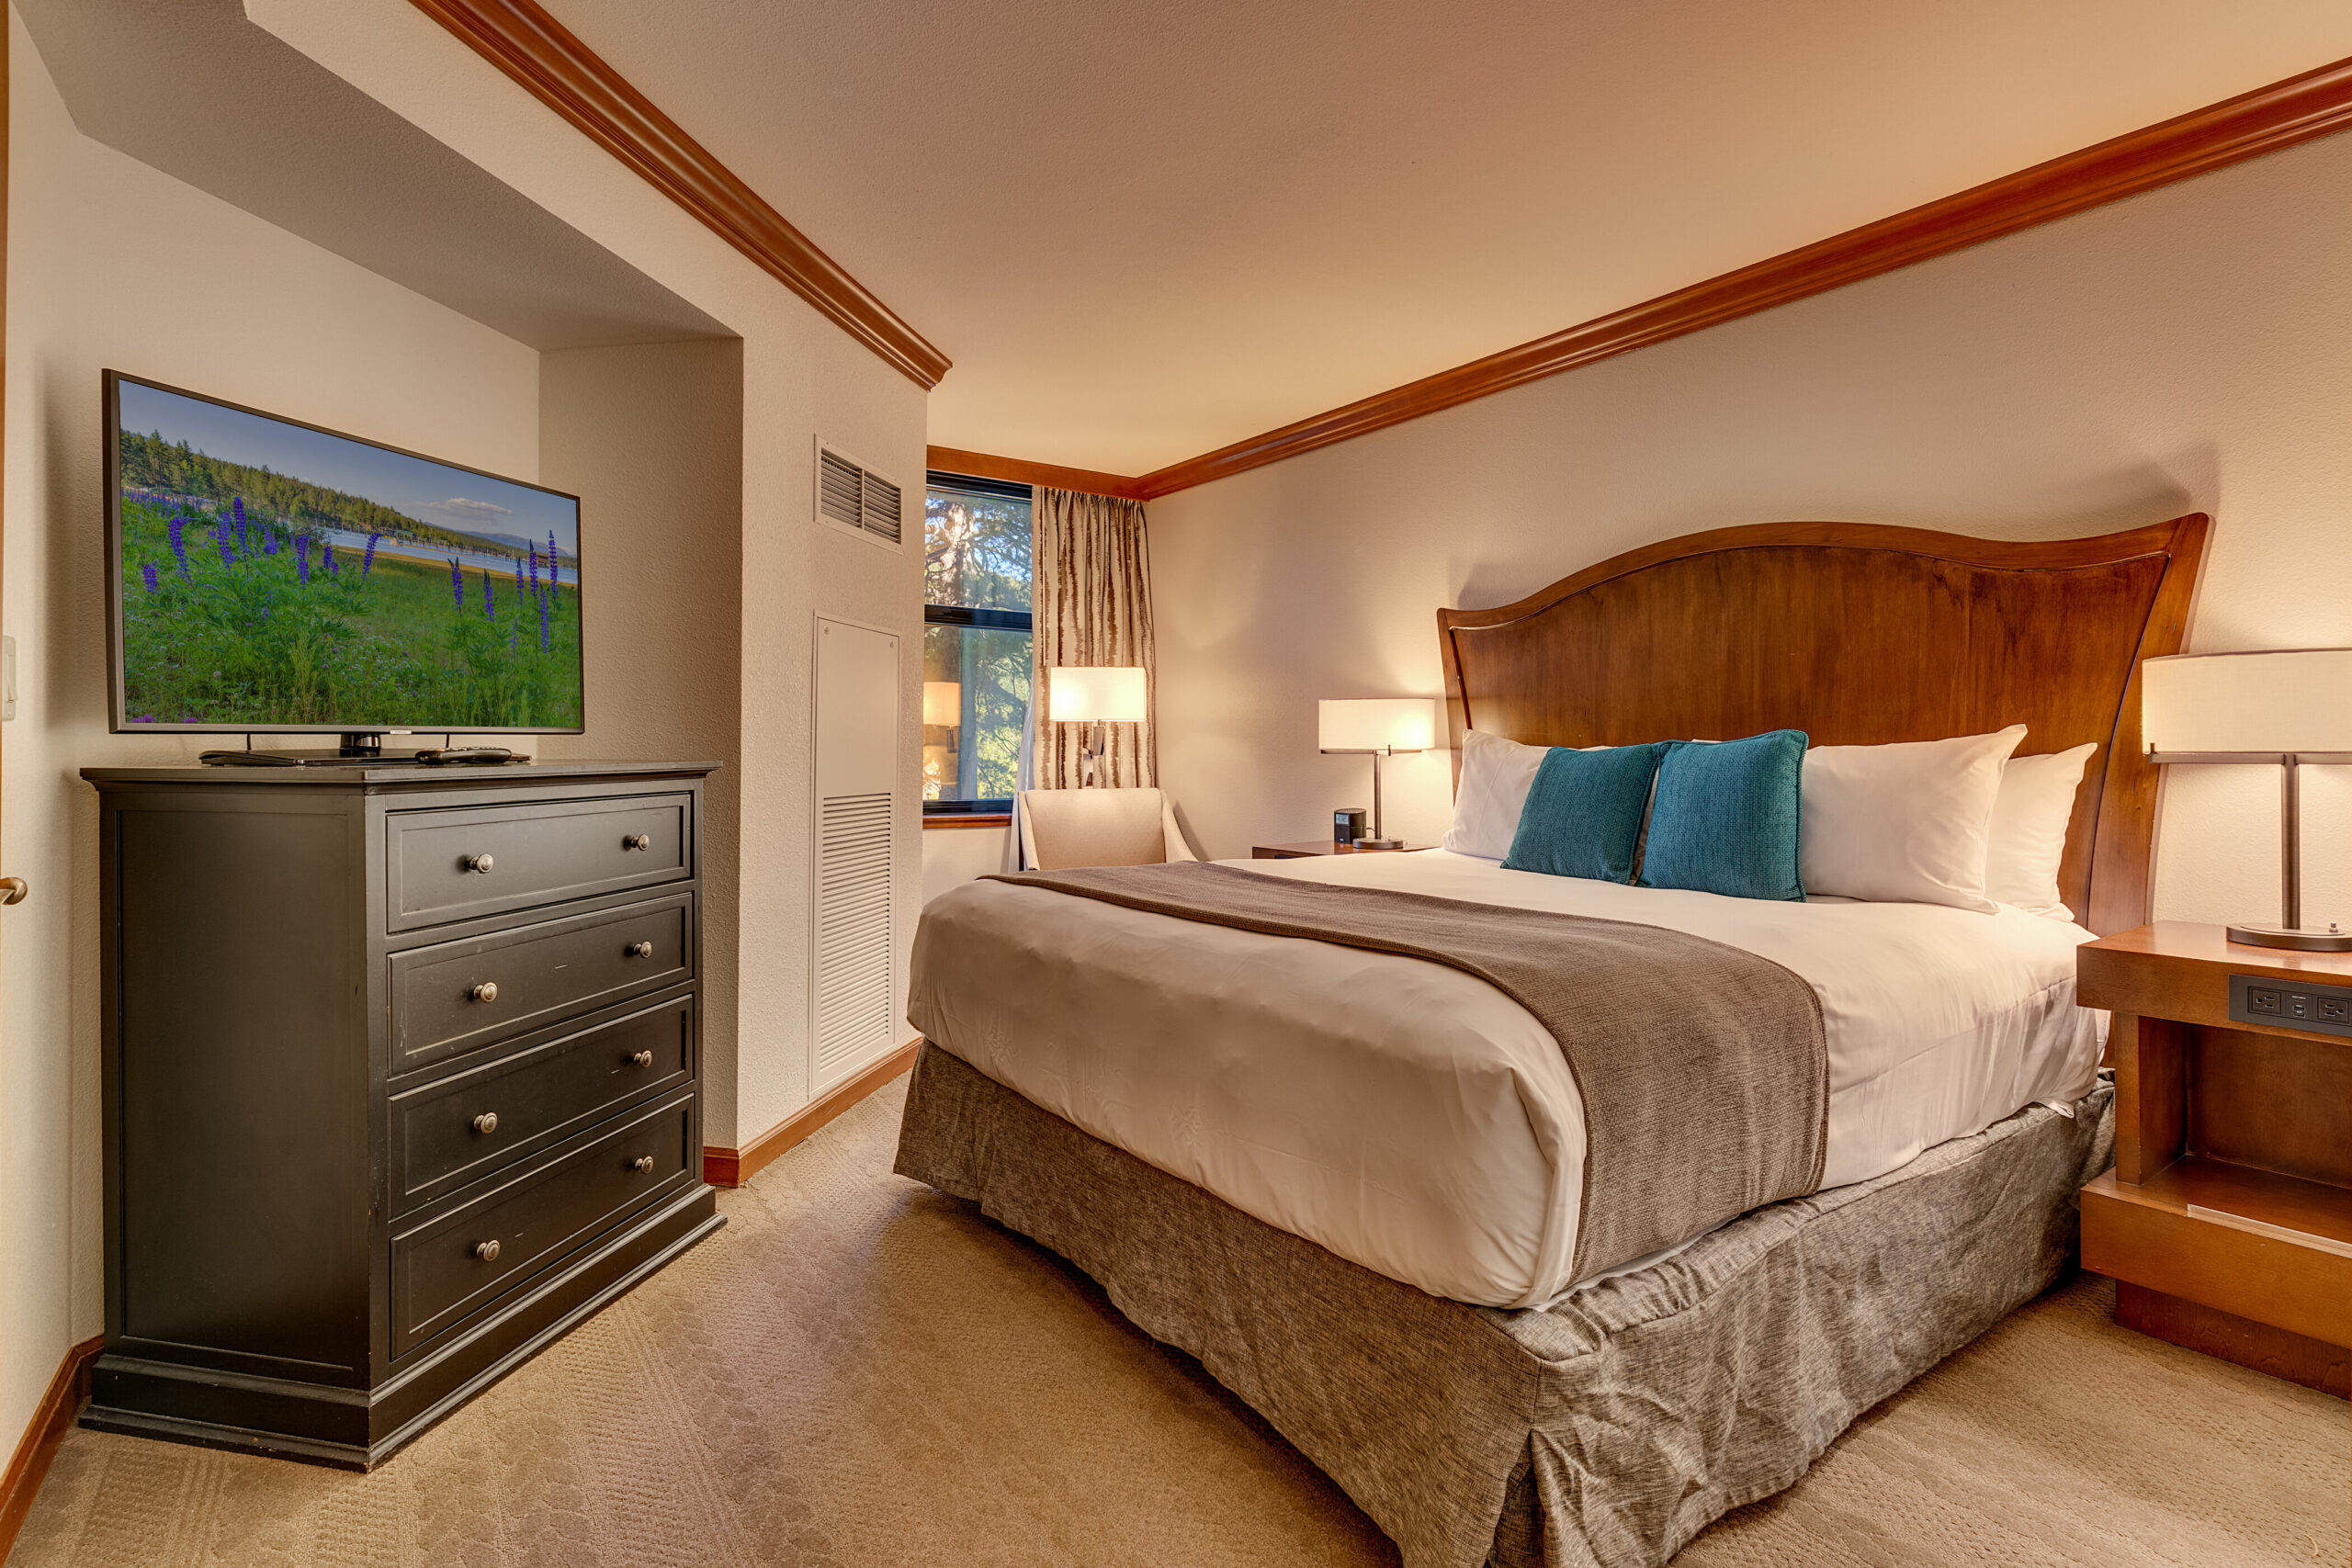
This beautiful two-bedroom condo has breathtaking views of the Olympic Valley area, Resort Chair, and mountain run. The one-bedroom fireplace suite offers a master bedroom with a king bed, a bathroom with a separate shower and tub, an owner’s locked cabinet with ample storage space, a kitchenette, and living and dining spaces. The second unit has two queen beds (ideal for rental opportunities for families) with a refrigerator and a bathroom with a tub and shower combo. You can lock off one bedroom/bath separately from the fireplace suite, offering a great balance between owner usage and rental opportunities.
The second-floor location has many benefits, including direct, ski-in/ski-out access — from the ski lockers conveniently located down the hall which then leads right outside to the chair lift. Après-ski hosted happy hours occur in the “Owner’s Lounge” located in the ski locker area. The second floor is also located on the same level as the loading/unloading area and free electric vehicle charging stations. Move right into your condo without having to go up and down the elevator! A laundry room and ice machine are located right across the hall. The Everline facility boasts many dining options, shopping, and recreational options year-round. Because of its concierge-style luxury resort experience and ample facilities, it’s also a wedding and conference destination. You will enjoy generating income when you are not enjoying your condo.
Located just a few blocks from Lake Tahoe Park, the private HOA beach and recreation area, this home is your idyllic West Shore retreat. The attached living space/kitchenette/bathroom has a separate entrance, and can be closed off from the main home. This extensively remodeled home has four bedrooms, four bathrooms, a separate living area, and ample space for you and all of your visitors. The fully fenced backyard and large deck allow maximum optimization for your outdoor time, no matter what the season.
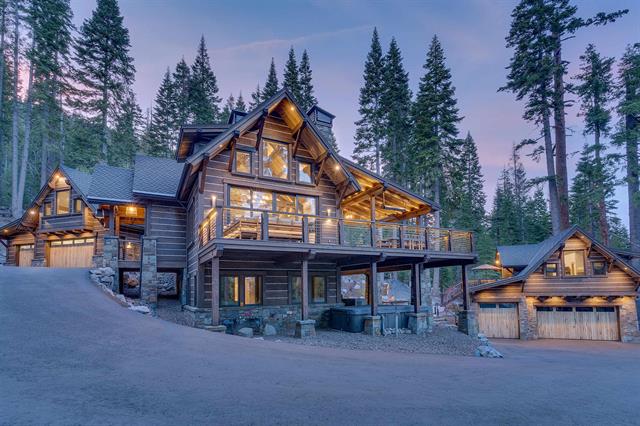
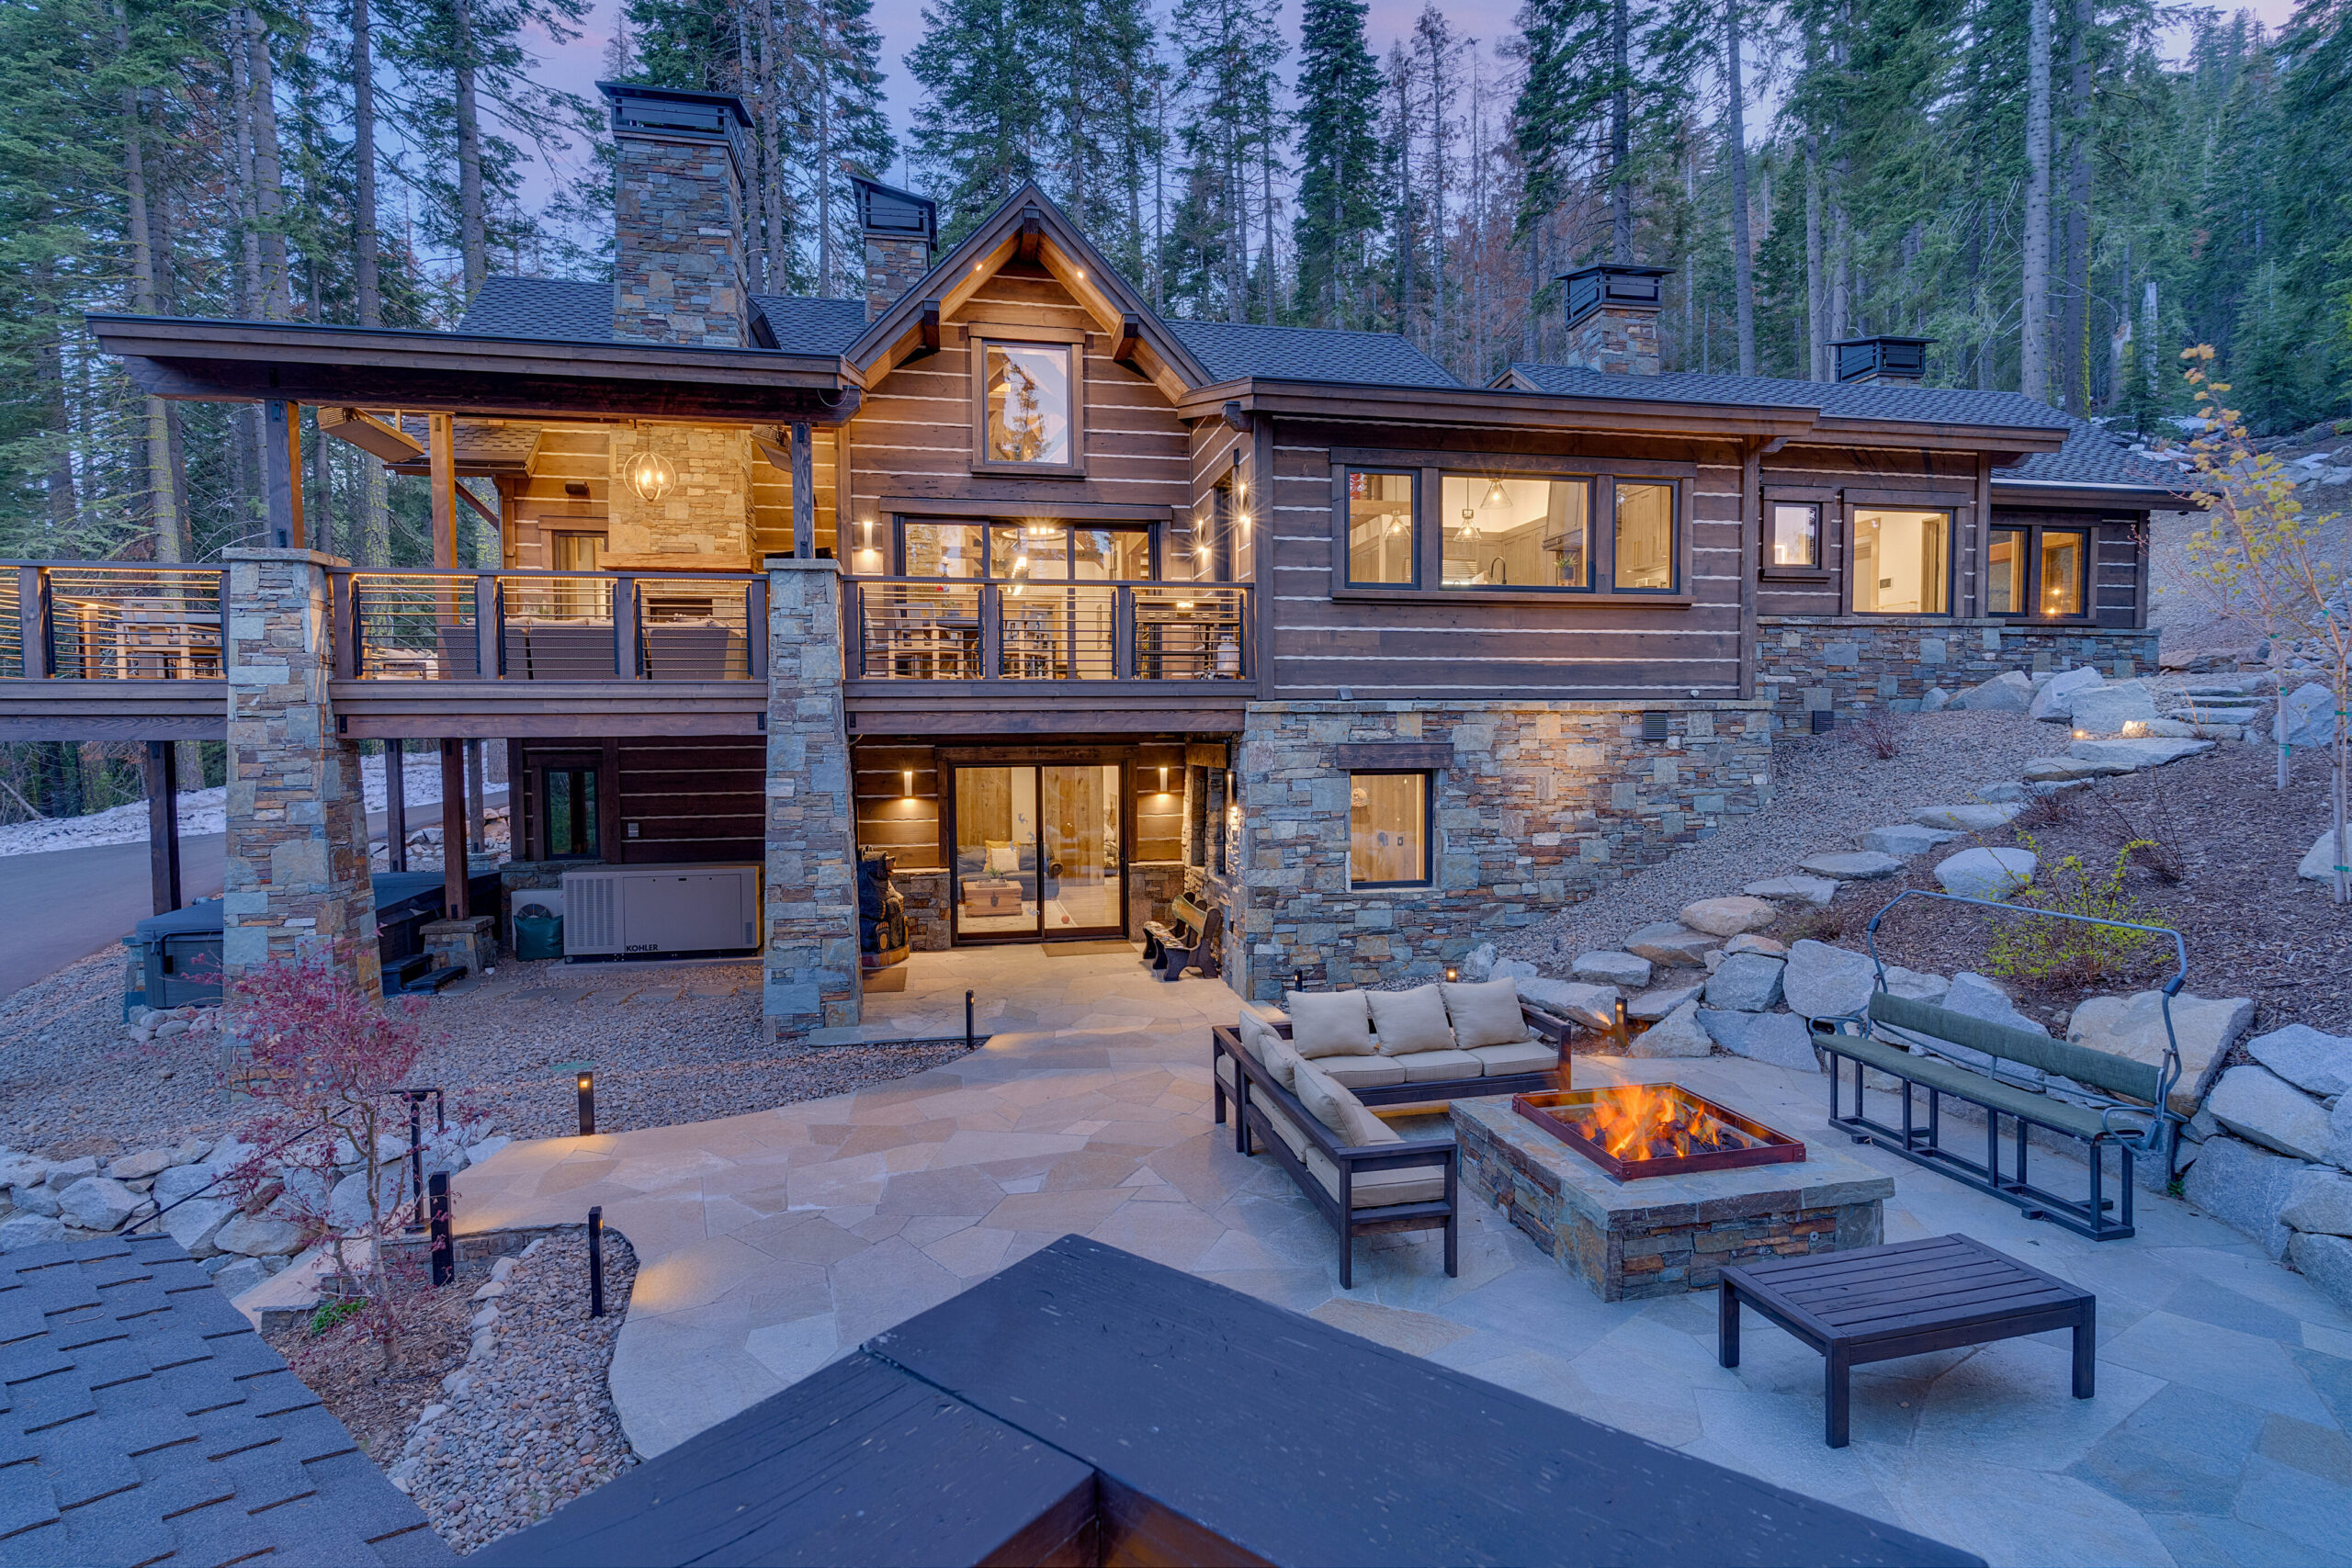
Beyond the A-symmetrical front gate lies 160 Cherry Street. Situated on 2.38 acres and backing to Forest Service land, this property encapsulates privacy and seclusion without compromising your proximity to the lake.
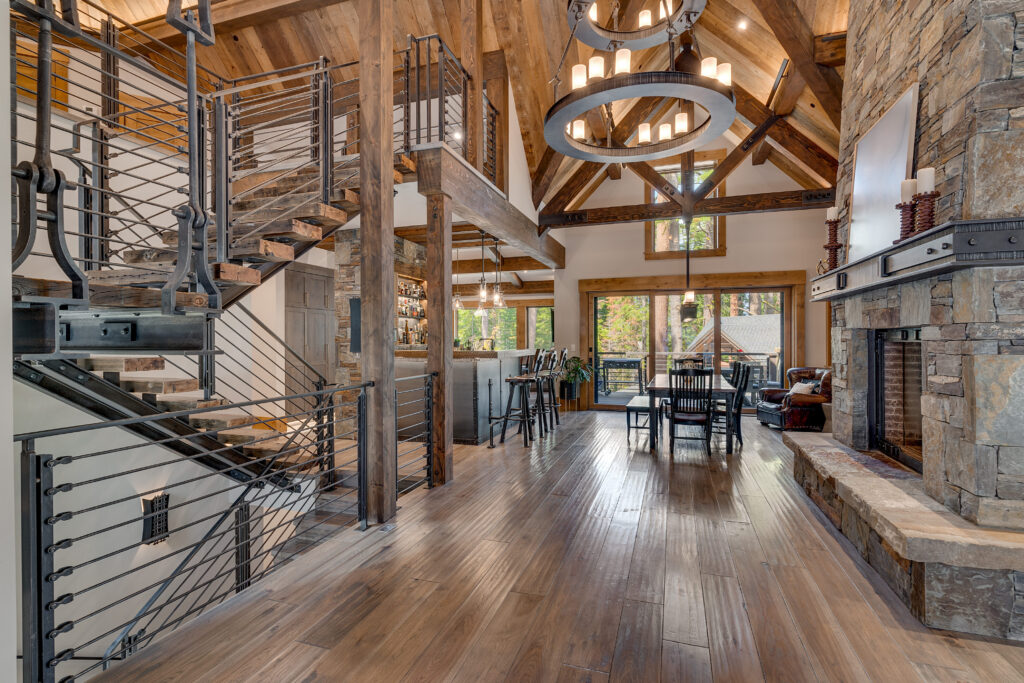
Completed in 2020, this home features endless unique components, such as a hanging staircase made out of forged steel, and the use of reclaimed wood from the original Tahoe Tavern Pier that was reworked for multiple pieces throughout this spectacular home. The 20-foot stone, floor-to-ceiling, double-sided fireplace centered in the great room is the heart for family gatherings and celebrations.
PRICE REDUCTION
160 Cherry Street, Homewood, California
6 BR | 5.5 BA | 5670 SF
Listing Price $9,800,000
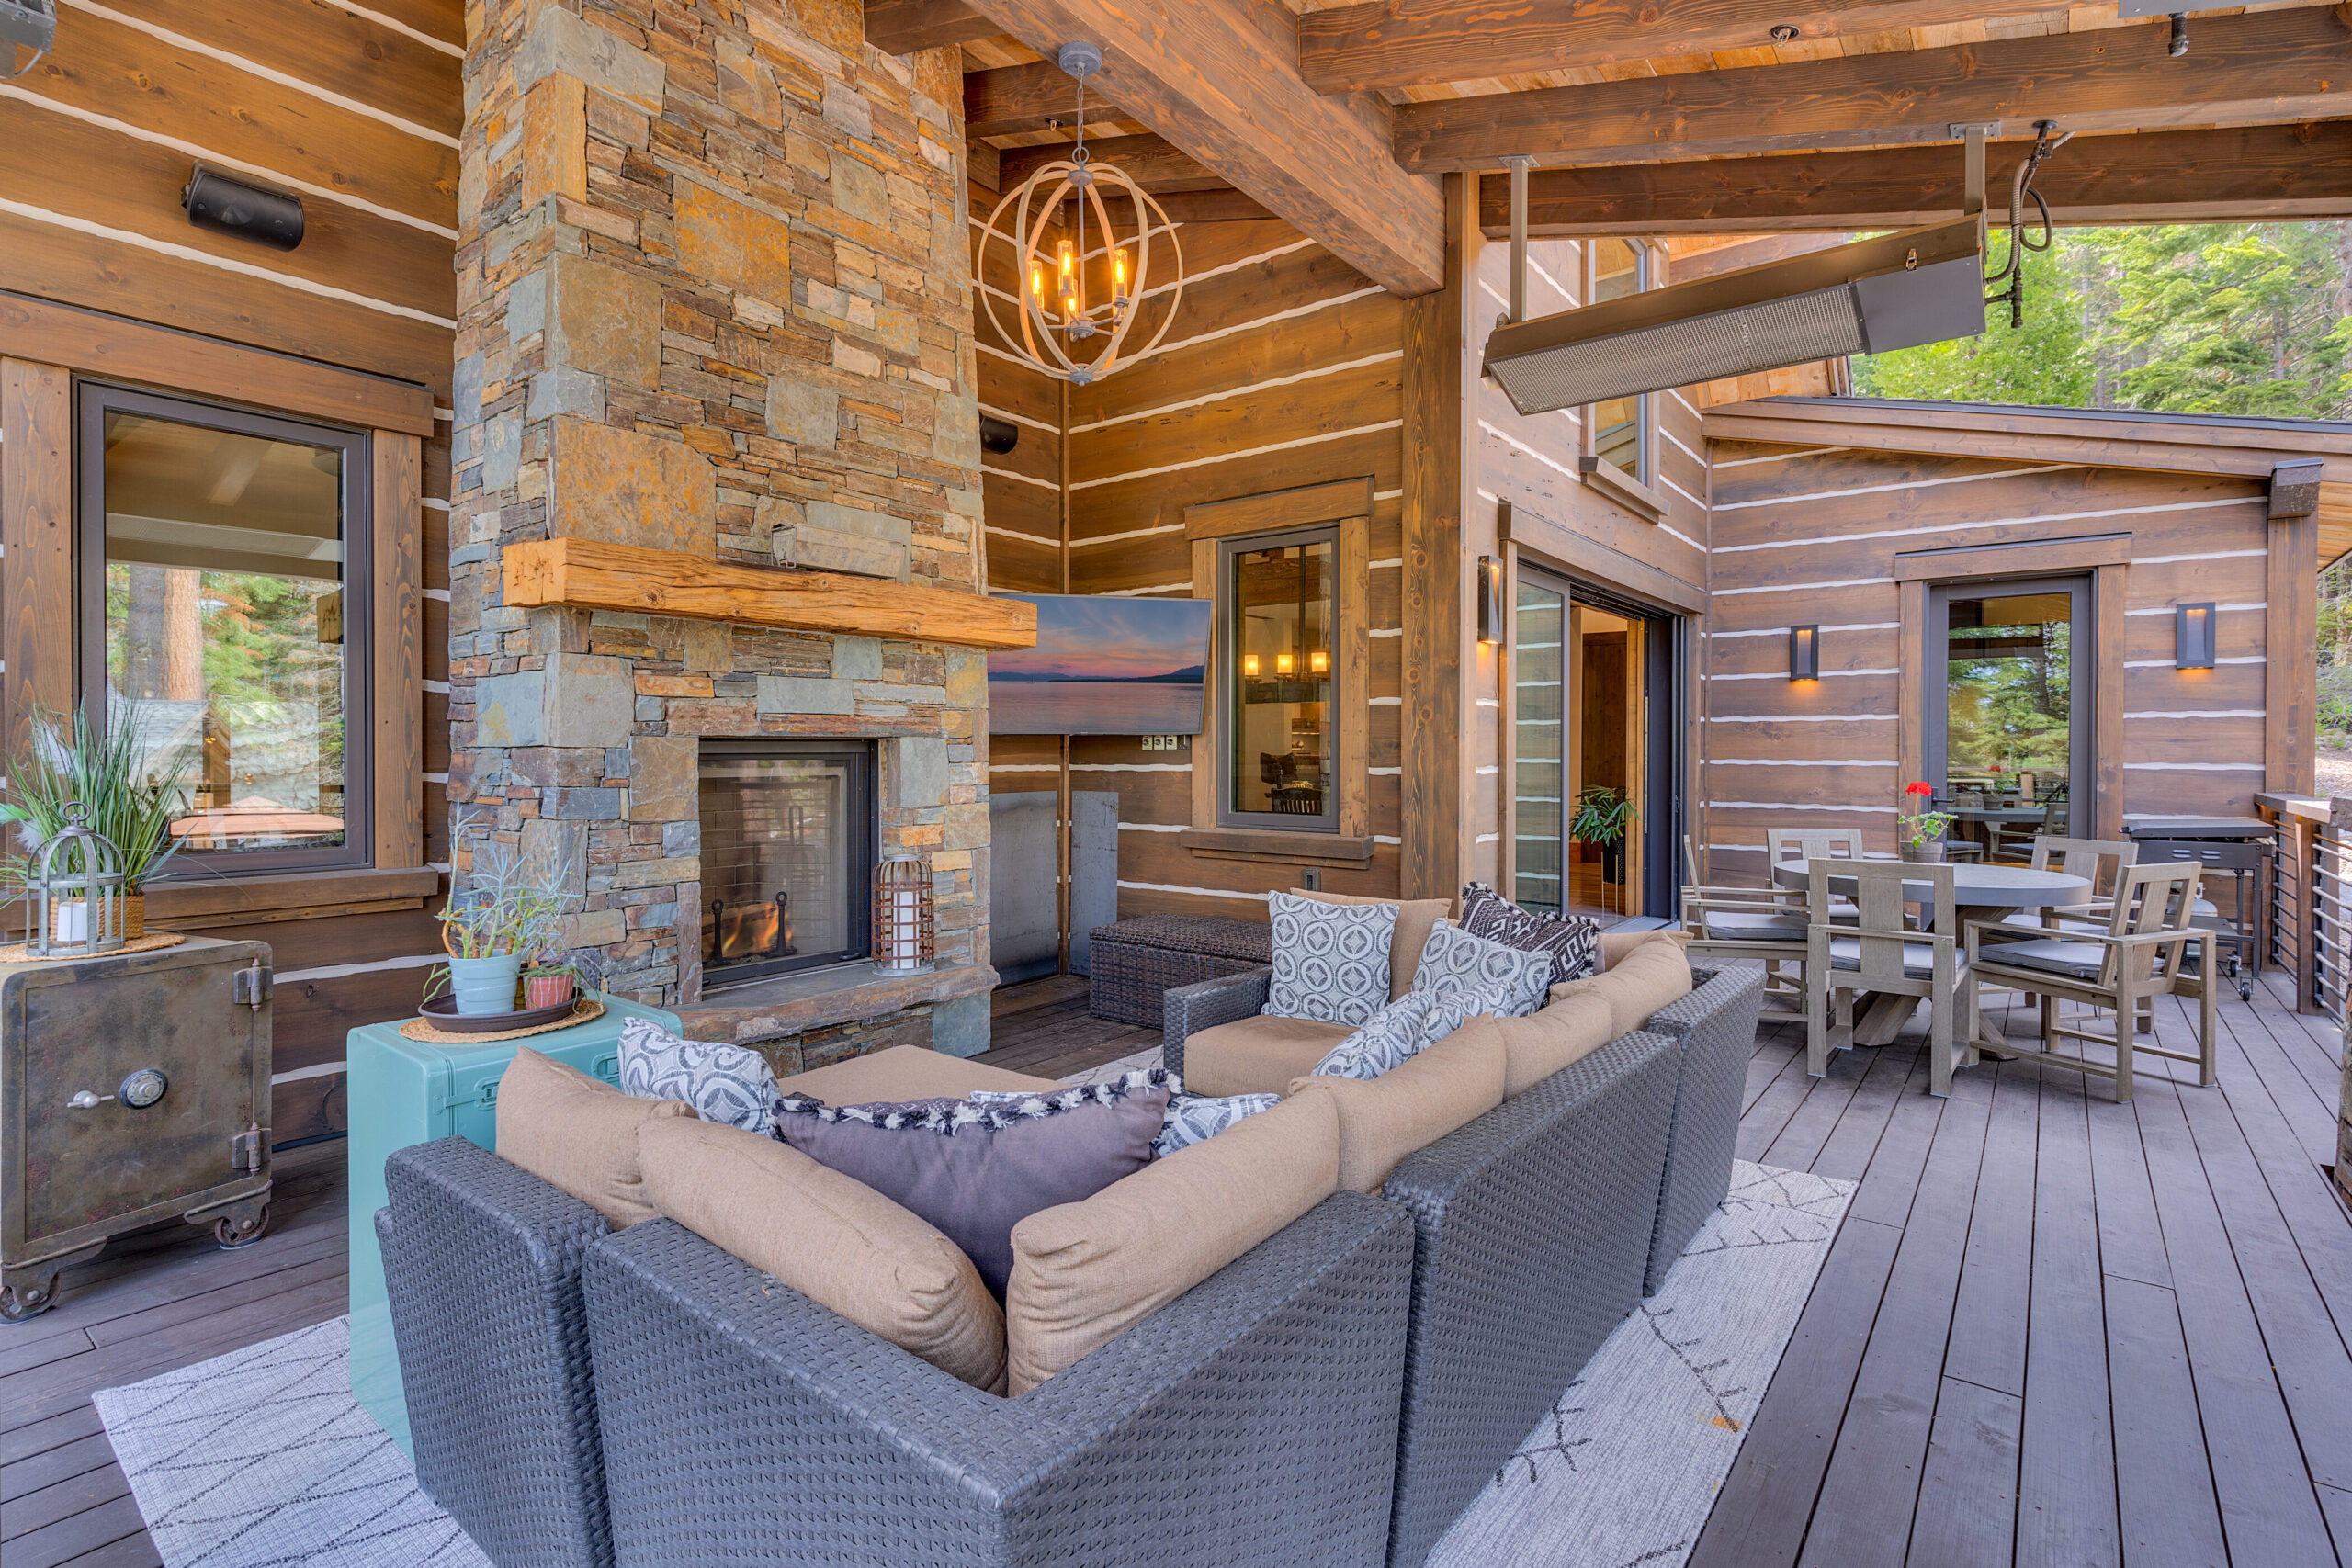
The main home has five bedrooms, four and a half bathrooms, and a 1,400-square-foot deck with a covered patio and wood-burning fireplace. The guest house is a fully detached one-bedroom, one-bathroom unit with four additional built-in bunk beds to accommodate both friends and family.
Nestled between the guest and main homes is an outdoor patio with a gas fireplace and a 30′ outdoor water feature. There are two separate garages that can comfortably house five cars and a boat. The radiant heat, air conditioning units, air purifying system, elevator, and heated stairs and driveway are the finishing touches to ensure life at Cherry Street is as effortless as it gets.
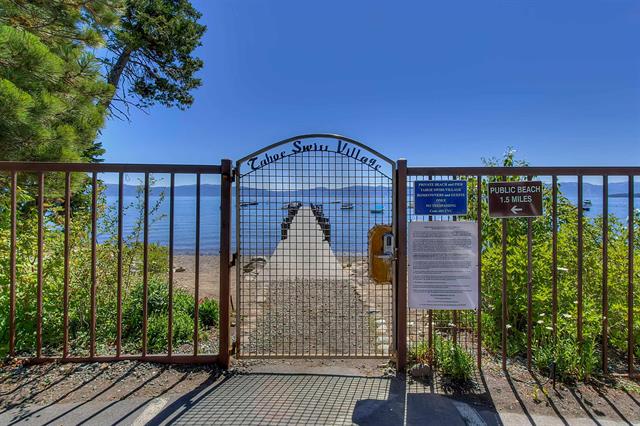
As a member of Tahoe Swiss Village’s homeowner’s association, you can enjoy the use of two buoys, two piers, and a private beach located just across the street. This custom home was initially envisioned as a mountain lodge with an industrial feel, and the dedicated group of minds behind it brought this vision to life. It was designed, engineered, and built by local teams who have a deep affinity for this area and worked together to seamlessly integrate the intimate characteristics of the home with the nature that surrounds it.
Located in Millcreek on a private parcel surrounded by matures pines, this fully renovated custom home is steps from Lakeshore Boulevard and a short stroll to the private beaches and amazing amenities. The new homeowners will enjoy full IVGID privileges and Nevada’s tax friendly residency. Nevada is one of only nine states that has no state income tax.
For more information on Incline Village real estate, contact Amie Quirarte.
This past week the Federal Reserve raised rates for the 10th time in a little over a year. Let’s discuss what happened as we await yet another Fed rate hike next Wednesday.
As we expected, the Federal Reserve raised the Fed Funds Rate to a range of 5.00% – 5.25%. Remember, this interest rate affects short-term loans like credit cards, autos, and home equity lines of credit.
The big question is whether this will be the last hike. When the Fed statement was released, the markets believed the Fed was signaling a pause by omitting the following line from the previous statement: “The Committee anticipates that some additional policy firming may be appropriate.”
However, shortly after the statement was released, Fed Chair Powell hosted a press conference and right at the top said the Fed Members have not discussed a “pause” in rates. Bottom line? Expect more uncertainty and volatility as it relates to rates.
Sound And Resilient
This is the term Fed Chair Powell used to describe the banking sector. Unfortunately, we are seeing more banks have issues. This week it was First Republic taken over by JP Morgan Chase and as of this writing PacWest was said to be “exploring strategic options.” The fear of banking contagion has elevated uncertainty in the financial markets. It’s not clear if and how many more banks will continue to have issues. Bottom line? The fear of this story has created a “safe haven” to trade into bonds where prices move higher, and rates move lower.
European Central Bank Hikes By Less
The European Central Bank (ECB) hiked their benchmark rate by .25%, the smallest since the start of their hiking cycle. Like our Fed, they too signaled they would be “data-dependent” going forward, leading markets to speculate a pause on future rate hikes.
Bottom line: The Federal Reserve is sending mixed messages on the future direction of rates. Meanwhile, long-term rates, which the Fed doesn’t control, are near their best levels in months and sense all the uncertainty in our economy will prompt the Fed to pause and potentially cut rates later this year. The incoming data and issues in the banking system will determine what happens next.
Looking Ahead
Expect market volatility to continue next week. The Consumer Price Index (inflation) will be reported. If this number comes in higher than expected, rates could rise. The opposite is true. Despite this being a backward-looking number, we will have Fed officials continue to speak and comment on the release and how they feel it impacts future Fed policy and interest rate decisions.
We’ve been getting a lot of questions about the new LLPA (loan level price adjustment) for Conforming loans and if people with worse credit will really get better rates than borrowers with excellent credit. The short answer is NO, and your clients should neverintentionally damage their credit. Surprise, surprise, there’s some entirely incorrect information circulating that your clients may be exposed to. Below is an explanation and FAQ’s:
What is changing?
Fannie May & Freddie Mac base pricing adjustments for credit scores & down payment are changing. Borrowers with a lower credit score & lower down payment will not be as heavily penalized. And, borrowers with best case scenario credit scores & down payment will receive less of a benefit than before. So, the difference in rates between best case credit profile vs. lower credit score will be less significant. These changes apply to every conforming loan funded by each & every mortgage company.
Does this mean borrowers with lower credit scores get better terms than those with higher credit score?
No. People will still be in better position with a better credit & more down payment. The difference between excellent & lower credit tiers will be less significant.
When does this go into effect?:
It’s been priced into rates for over a month now. The May 1st date is when these adjustments go into effect for the mortgages purchased on the secondary market by Fannie/Freddie. Banks knew this was coming, so these changes have already priced in and borrowers will not see any changes to rates over the next week, outside of the normal day to day bond/rate fluctuations.
What is the FHFA trying to achieve with these pricing adjustment?
We all know Fannie/Freddie’s mission to increase access to affordable housing. It’s always been their mission and it’s been a priority for the director of FHFA. The new director of the FHFA has been vocal in disapproval of the solutions provided by Franny and Freddie and she thinks more is required of them to increase access to affordable housing, and she thinks this will help increase access to affordable housing.
Is this a good idea and will it work?: We don’t like it but the whole world has to deal with it, so it is what it is at this point. We do not see these pricing changes moving the needle in making homeownership more attainable for more Americans because even after these changes a borrower with low 600’s credit score is still better off going with an FHA loan, and those who have done a great job managing credit are stuck a hair worse pricing. A better idea would be a campaign to educate people on how to manager credit; it’s not complicated and the information could be shared on something as simple as this one page I put together and have been sharing with clients for over a decade (see attached). WE (all of us on the real estate community) continue to be the front lines in educating the public on all things related to buying, investing, & enjoying real estate.
If you want to dig into the details, here are some example of scenarios that will be most affected: Attached is a matrix showing which scenarios have pricing improvements (green) vs. hits (red), relative to the old standard LLPA’s.
LTV’s in the 80% – 85% range are most significantly affected, so more borrowers in the ~19.99% – ~15% down might consider just doing 10%.
Cash-out refinances hits are mostly greater, unless you have top tier (>780) credit, or extremely low LTV (<30%). So, cash-out refi is actually a scenario where if credit is >780, pricing adjustments have improved.
Price improvements for 2 & 3 unit properties.
Price improvements for low LTV investment properties.
Vacation Homes & Investment Properties essentially priced the same now.